ATM Cash Advance・Instant Money

Screenshots
Details
- Rating
- 14.20K reviews
- Version
- 2.139.0
- Developer
- ATM.com, Inc.
Analysis by Norviv
When an unexpected bill lands between paydays, I understand why a cash advance app can feel more practical than applying for a traditional loan. ATM Cash Advance・Instant Money is built around that narrow, urgent moment: it is a free finance app from ATM.com, Inc. that lets eligible users request access to cash advances without a conventional credit check. I would not treat it as a replacement for a budget, savings account, or regular income, but I found its value easier to understand when I looked at it as a short-term bridge rather than easy extra money.
The app has attracted a 4.5 average from around 54 thousand ratings and has passed one million installs, which suggests that its basic idea is resonating with a substantial audience. It is available to an Everyone audience, and the current Android release is version 2.139.0, supporting devices running Android 8.0 or later. Those details make it reasonably accessible, although eligibility for an advance is a separate question from being able to install the application.
How I would use it in a normal week
My starting point with ATM Cash Advance would be deliberately simple. I would install it, create or access my account, review the information it requests, and look carefully at the amount available before accepting anything. The important habit is to begin with the repayment date and the total obligation in mind, not with the maximum amount the screen happens to show. A cash advance solves a timing problem; it does not solve a recurring shortfall.
For a realistic example, imagine that a utility payment is due two days before payday and the account balance is temporarily low. I would first check whether the payment can be moved, whether a biller offers a grace period, or whether a small transfer from savings is less costly. If those options are unavailable, I would use the app only for the precise gap, record the expected repayment, and avoid treating the remaining displayed availability as spending money.
That distinction is the first useful workflow improvement. I would write down three things before proceeding: the amount needed, the date the money should be available to repay it, and the recurring expenses that will arrive before then. This takes less time than dealing with a repayment surprise. It also prevents the common mistake of borrowing for a general shopping trip when the original need was a single bill.
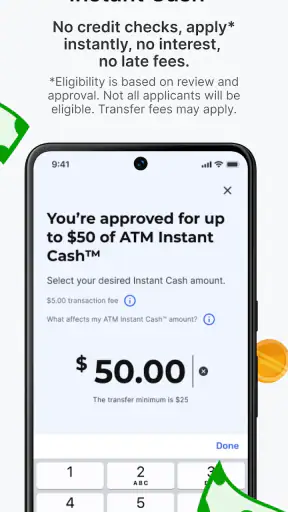
The app’s “no credit check” positioning may appeal to people who have limited credit history or do not want a traditional lender inquiry to determine access. Still, that phrase should not be read as “no conditions.” A user should expect the app to evaluate the account and request information needed to determine eligibility. I would read every on-screen explanation about an advance, repayment, account connection, and any applicable charge before confirming.
I also would not assume that installing the app guarantees an instant advance. The store summary describes access to instant cash advances, but actual availability can depend on the user’s situation and the app’s review process. In practice, I would open it before an emergency, not during the final minutes before a payment is due. That gives me time to understand the flow and consider a backup option.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
What I would check before accepting money
The most important screen is the one that explains what happens after an advance is accepted. I would look for the repayment timing, the amount that will leave my account, and whether the transaction is optional or scheduled through an arrangement I need to understand. I would also check whether the amount shown is the amount I receive or the amount I must repay, because those figures are not always the same in financial products.
I would take a screenshot or note the confirmation details for my own records, especially if I were using the service for a bill with a fixed due date. That is not a special feature claim; it is a practical safeguard. If the app later shows a different status, having the original information makes it easier to trace what I selected.
Another useful step is checking the bank account connected to the service. I would make sure it is the account I actually use for incoming pay and repayment, rather than an old account that still appears in a financial app. I would also avoid changing the linked account immediately before repayment unless the app clearly explains how that change affects an existing advance.
Notifications deserve attention too. I would keep reminders enabled if the app offers them, because short-term borrowing becomes much riskier when the repayment date disappears from view. At the same time, I would not rely only on push notifications. I would add the expected repayment to my normal calendar or banking routine, since phone alerts can be missed, delayed, or buried under other messages.
Settings and account habits worth checking
Experienced use of this app is less about tapping quickly and more about keeping the account tidy. I would review the profile and notification settings after setup, confirm that contact details are current, and make sure I understand which alerts relate to account activity and which relate to promotional messages. Clear alerts are useful; a crowded notification stream makes important repayment information easier to overlook.
I would also inspect the app after an advance rather than uninstalling it immediately. The account history or status area, where available, is the natural place to confirm that the transaction is recorded correctly. If I had more than one advance or account event, I would check each entry separately instead of assuming that one successful screen represents everything.
A small but valuable habit is to use the same personal naming system outside the app. For example, I might note “rent bridge” or “car repair” beside the date in my budget. That keeps the advance connected to its purpose and makes it obvious whether I am using the service for isolated timing issues or repeatedly covering the same category. The latter is a warning that the underlying budget needs attention.
I would not change notification, bank, or profile details while rushing through a request. Financial apps reward slow confirmation. Before pressing the final button, I would reread the amount, the expected repayment, and the account involved. A few extra seconds are worthwhile when the result affects a real bank balance.
Because the app is free to download, I would separate the app’s price from the cost of using a cash advance. “Free” describes installation, not necessarily every possible transaction or service condition. I would review the current terms shown in the app before accepting an advance, especially if the screen presents optional services, expedited access, or any charge. This is one of the places where a traditional bank overdraft, a credit union option, or borrowing from a trusted person may be cheaper.
Faster patterns that still keep control
Once I understood the normal workflow, I would make it repeatable rather than improvising each time. My pattern would be: open the app, review the current account status, compare the available amount with the exact bill, check the repayment impact on payday, and then decide. The speed comes from having the questions ready, not from skipping them.
I would keep a small emergency note on my phone with the bills that can genuinely wait, the bills that cannot, and the amount I can repay without affecting food, transport, or housing. That note helps me avoid using the app simply because the interface makes access feel convenient. A fast decision is only useful when it is still a good decision.
Another practical pattern is to check the app during ordinary financial housekeeping, not only when stressed. I would review the account after payday, reconcile any completed advance with my bank transaction list, and remove the obligation from my personal budget once it is settled. This creates a clear cycle: request only when needed, monitor while active, confirm repayment, and then return to normal spending.
I would also avoid stacking decisions. If one advance is already active, I would not immediately request another to cover a separate purchase unless I had written down how both affect the same income date. Two small obligations can create more pressure than one larger, planned expense because they are easier to forget individually. The app may make access straightforward, but the responsibility for the combined budget remains mine.
For users who receive irregular income, the app may be more useful as a last-resort timing tool than as a routine payday supplement. I would compare the expected income date with the repayment schedule and leave room for delays. If my income frequently changes, I would be especially cautious about accepting an obligation that assumes a perfect payday.
The same reasoning applies to people with shared finances. I would discuss the advance with anyone who relies on the linked account before accepting it. A repayment that looks manageable in isolation can interfere with groceries, childcare, or a joint bill. The app is personal in its interface, but the bank balance may support an entire household.
Where the convenience reaches its limits
The biggest limitation is that a cash advance is still borrowed money. Avoiding a conventional credit check may make access feel less intimidating, but it does not remove the need to repay. I would skip the app if I already knew that my next income will not cover the advance and my essential expenses. In that situation, a debt counselor, creditor payment arrangement, employer assistance program, or local support service may be more appropriate.
I would also be cautious if I needed a large amount, a long repayment period, or a predictable monthly loan. ATM Cash Advance is better suited to a short gap than to financing a major purchase. A bank personal loan, credit union product, or structured payment plan may offer clearer long-term terms for a larger obligation, even if the application takes longer.
Users should distinguish speed from certainty. The app’s focus on instant access is attractive when timing matters, but an urgent request is exactly when people are most likely to overlook conditions. I would never accept an amount merely because it is available. I would decide the amount from the bill and my repayment plan, then stop.
There is also a psychological limit. Seeing a balance or advance amount inside a polished mobile interface can make borrowed funds feel similar to earned funds. I would treat every advance as a separate liability in my own budget. That mental separation is more important than any shortcut because it determines whether the app remains a safety valve or becomes part of a cycle.
The age rating of Everyone makes the app broadly accessible from a content perspective, but financial suitability is not the same as content suitability. I would recommend that younger or financially inexperienced users involve a trusted adult before accepting an advance. The interface may be easy to navigate while the consequences of repayment are still significant.
Android users should also pay attention to compatibility. The app supports Android 8.0 and later, so someone using an older phone may not be able to install the current release. On a supported device, I would keep the operating system and the app updated through the normal store process, particularly when handling account and financial information.
How it compares with familiar alternatives
Compared with a traditional bank overdraft, ATM Cash Advance may feel more focused because the request is presented as a separate short-term action rather than as a feature of the checking account. That can make the purpose easier to see, but it also means I would need to understand the app’s own repayment conditions instead of relying on familiar bank rules.
Compared with a credit card cash advance, the app’s appeal is that it is designed around access without a conventional credit check. A credit card may be more convenient for someone who already has available credit and understands its terms, while this app may be more relevant to someone who does not want to use or cannot access that route. Neither option should be judged by speed alone; the total cost and repayment pressure matter more.
Compared with borrowing from a friend or family member, the app offers a formal digital process and avoids an awkward personal conversation. The trade-off is that a personal loan may be more flexible about timing and cost, while an app-based obligation requires careful attention to its stated conditions. I would compare the emotional cost of asking for help with the financial cost of the advance, rather than assuming one is automatically better.
Compared with building an emergency fund, the app is a response tool, not prevention. I would use it only while working toward a small cash reserve. Even setting aside a modest amount after each payday can reduce how often I need an advance, which is ultimately a stronger financial improvement than becoming faster at requesting one.
ATM.com, Inc. has positioned this product clearly within personal finance, and the app’s large install base shows that the use case is familiar. Still, popularity does not make every advance suitable for every person. I would judge it by whether the repayment fits my actual cash flow, not by the number of people who have downloaded it or the strength of its average rating.
My verdict after looking at the complete workflow
I see ATM Cash Advance・Instant Money as a potentially useful emergency bridge for someone who needs a small amount quickly, understands the repayment obligation, and does not want a conventional credit check to be the first gate. Its free installation, accessible age classification, and straightforward cash-advance focus make it easy to consider when a short timing mismatch appears.
My recommendation comes with a firm condition: use it with a written purpose and a repayment plan. The strongest users will check the linked account, review notifications, record confirmation details, and monitor the advance until it is fully settled. They will also compare the app with a bill extension, savings, a bank option, or personal help before borrowing.
I would skip it for ongoing overspending, major purchases, uncertain income, or any situation where repayment would endanger essentials. In those cases, the convenience can hide the real problem instead of fixing it. For an isolated gap that can be repaid comfortably, however, the app can be a practical tool when used carefully.
My final view is balanced: this is not free money and it is not a substitute for financial planning, but it can make a short-term cash problem more manageable. The best way to use ATM Cash Advance is to make the borrowing decision slower than the money transfer. That one habit keeps the app in its proper role: a controlled backup for an occasional emergency, rather than a routine part of everyday spending.
Frequently Asked Questions
01What is ATM Cash Advance・Instant Money, and how does it work?
ATM Cash Advance・Instant Money is a financial app designed to help eligible users request short-term cash advances through a mobile device. After creating an account, you generally provide personal and financial information, review available offers, and select the amount and repayment terms. Approval, transfer speed, and available features can vary depending on your location, credit profile, and the provider’s requirements.
02Is ATM Cash Advance・Instant Money a free app to use?
Downloading the app may be free, but using a cash advance service is not necessarily free. Depending on the offer, you may encounter service charges, transaction fees, subscription costs, interest, or other expenses. Before accepting any advance, carefully review the total repayment amount, due date, recurring payment conditions, and applicable fees shown in the app or agreement.
03How quickly can I receive money through the app?
The app may advertise fast access to funds, but delivery is not guaranteed to be immediate. The timing can depend on identity verification, approval procedures, banking hours, weekends, your financial institution, and the selected transfer method. Some users may receive funds quickly, while others may experience delays or require additional documentation before the request is completed.
04What information and eligibility requirements are needed to apply?
Applicants may need to provide identifying details, contact information, employment or income information, bank account data, and permission for certain verification checks. Eligibility can depend on age, residency, a valid bank account, regular income, and other criteria established by the lender or service provider. Requirements and availability may differ by state, country, and individual circumstances.
05What should I know about repayment and privacy before downloading?
Before using ATM Cash Advance・Instant Money, read the privacy policy, permissions, terms of service, and repayment agreement carefully. Confirm how your information is collected and shared, whether payments are automatically withdrawn, and what happens if you miss the due date. A late payment may result in additional charges, account restrictions, collection activity, or negative consequences depending on the provider.


